Mortgage and protection advice, from your first home to your next move
We’re a fee-free mortgage broker, authorised by the FCA. We advise on buying, moving, remortgaging and buy-to-let, including self-employed income and past credit problems, and we arrange life insurance, critical illness cover and income protection. Talk to us by phone or video, wherever you live in England or Wales.
- No advice fee
- 900+ clients
- ★ 5.0 from 59 Google reviews
No advice fee. Lender, valuation and legal costs may apply. Your home may be repossessed if you do not keep up repayments on your mortgage.
What our clients say
Real reviews from people we’ve helped with their mortgages.
“I honestly cannot recommend Jordan at The Mortgage Hive highly enough. He has been absolutely amazing throughout the whole remortgage process… Jordan always took the time to explain everything clearly and never made me feel like I was asking a silly question.”
“We’ve used Paul’s services twice now… Paul gave us some options we didn’t even realise were available to us… It was a complex case involving a Buy-to-Let mortgage, but Paul explained everything in detail.”
“I have used Jordan for 6 years. We have remortgaged, borrowed more and now looking to self build. He is professional and informative. Wouldn’t go anywhere else.”
Ready to talk? Request a call back
Mortgage advice for buying, moving, remortgaging and letting
Pick the route that fits what you’re planning. Each page explains how it works, what lenders look at and how we can help.
First-time buyers
Understand deposits, affordability and what documents lenders may need before you start viewing.
First-time buyer mortgages →
Moving home
Check what you could borrow, whether to port your current deal and what the move will cost.
Moving home mortgages →
Remortgage
Review your current mortgage, compare new options and plan ahead before your existing deal ends.
Remortgage advice →
Product transfer
Compare a new deal with your current lender against moving elsewhere, before your rate ends.
Product transfers →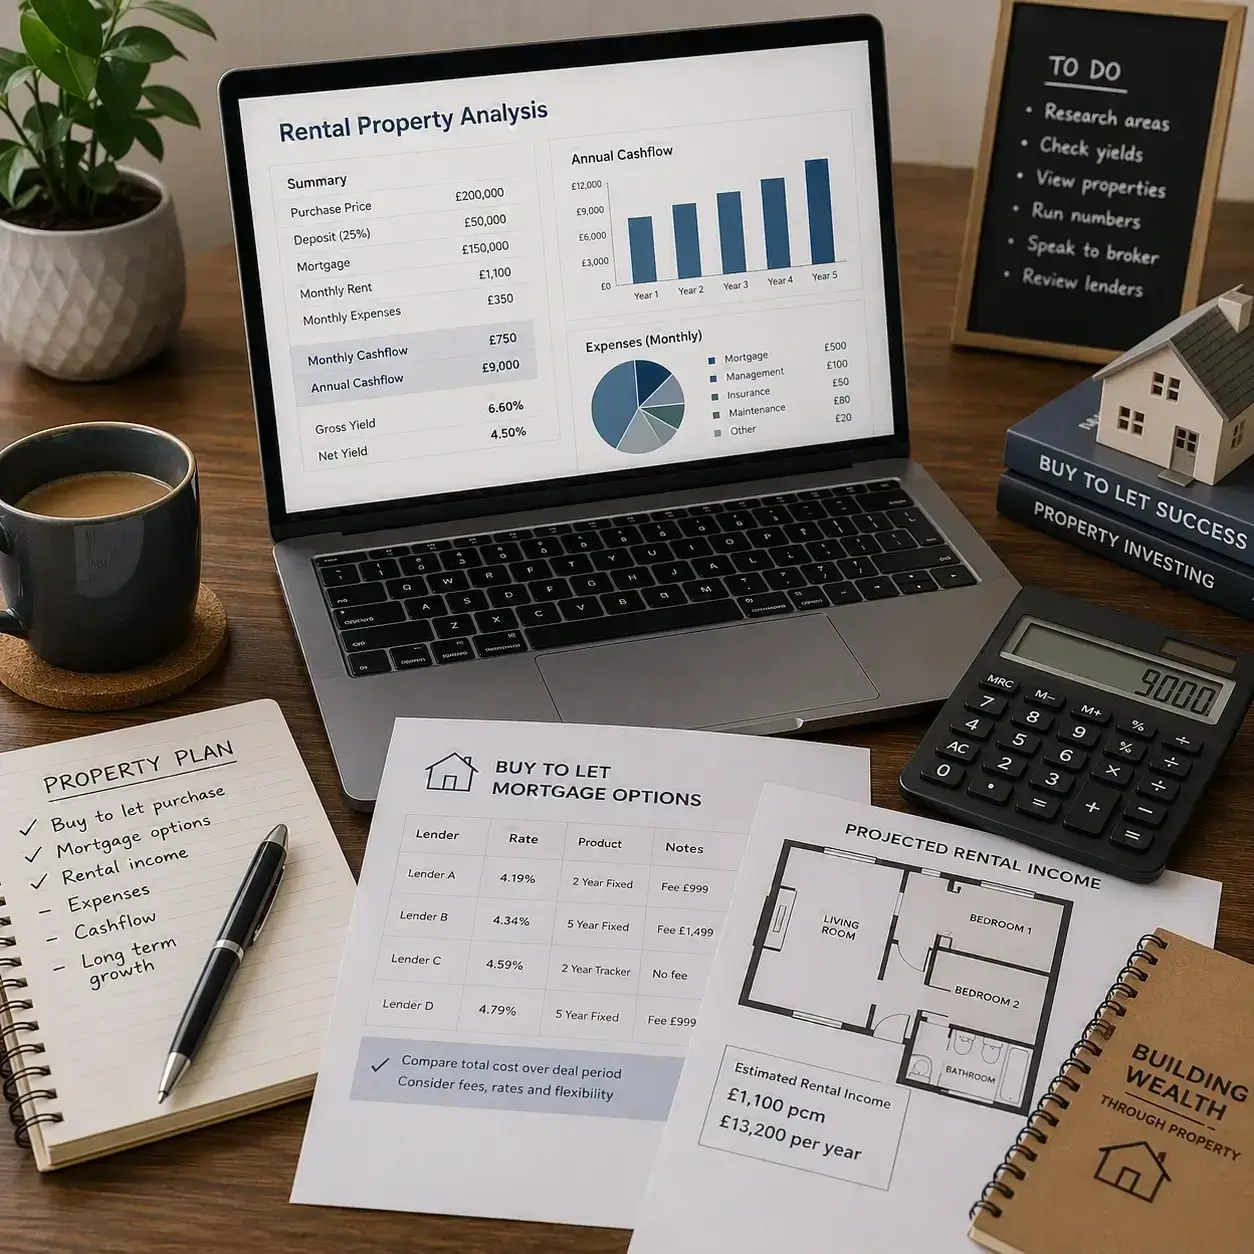
Buy-to-let
Advice for new and portfolio landlords, limited company borrowing and buy-to-let remortgages.
Buy-to-let mortgages →
Key workers
Mortgage advice for NHS staff, teachers, the emergency services and other key workers.
Key worker mortgages →Specialist and complex mortgages
Self-employed, a past credit problem or income from several places? These can narrow the choice of lenders, but they don’t always rule you out. We look at specialist lenders as well as the high-street names.
Income that needs explaining
Past credit problems
Life insurance, critical illness cover and income protection
Your mortgage payments carry on if your income stops. The right cover can help your family keep up the payments if you die, fall seriously ill or can’t work.
Life insurance
Pays out if you die during the term of the policy.
Critical illness cover
Pays out if you’re diagnosed with a specified serious illness.
Income protection
Replaces part of your income if you can’t work because of illness or injury.
We can review your cover alongside your mortgage, or on its own.
Equity release advice for homeowners aged 55 and over
A lifetime mortgage is a loan secured on your home that lets you release money while you carry on living there. The loan and any interest added to it are usually repaid from the sale of your home when the last borrower dies or moves into long-term care.
We explain the alternatives first, including downsizing and retirement interest-only mortgages. Family are welcome at the meetings.
Equity release includes lifetime mortgages and home reversion plans. To understand the features and risks, ask for a personalised illustration. Equity release will reduce the value of your estate and may affect your entitlement to means-tested benefits.
Equity release advice is available in England only.
Mortgage calculators and tools
Get a rough idea of the numbers before you speak to us.
How much can I borrow?
A first look at what lenders may offer on your income.
Mortgage repayment calculator
Compare monthly payments over different terms.
Stamp duty calculator
Estimate the stamp duty on a purchase.
Remortgage calculator
See how a new deal could change your payments.
Buy-to-let mortgage calculator
Check how rent and borrowing fit together.
All calculators
Every mortgage and protection calculator in one place.
How our mortgage advice works
- We talk it throughBy phone, video or in person. We look at your income, deposit, credit history and plans.
- We compare and explainWe compare options from over 100 mainstream and specialist lenders, and explain the costs and what each option means for you.
- We handle the applicationWe deal with the paperwork, the lender, the valuer and your solicitor, and keep you updated through to completion.
Fee-Free Mortgage Advice
- No advice fee. Lender, valuation and legal costs may apply.
- We don’t charge a broker fee. We’re paid by the lender or provider. Lender, valuation and legal costs may apply.
- Open, honest, straight-talking guidance
- A named adviser from your first call through to completion
- Online, over the phone or face to face
100+ mainstream and specialist lenders, including
- Halifax
- Nationwide
- Barclays
- Santander
- Leeds Building Society
- Skipton Building Society
- Kensington
- Accord
- Precise
- Coventry
- Aldermore
- Newcastle Building Society
- Scottish Widows Bank
- West Brom
- Family Building Society
What is a Decision in Principle?
A Decision in Principle (also called an Agreement in Principle, Mortgage in Principle, AIP or DIP) is a lender’s early indication of how much it may lend, based on the details you give. It helps you set a realistic budget before you view or make an offer.
Mortgage guides and answers
Plain-English guides to help you understand your options before you speak to us.
Buying a home
Guides for first-time buyers and home movers.
Deal ending
Remortgage and product transfer guides.
Buy-to-let
Guides for new and existing landlords.
Self-employed
How lenders look at self-employed income.
Credit problems
Getting a mortgage after missed payments, CCJs or defaults.
Key workers
Guides for NHS staff, teachers and the emergency services.
Speak to Jordan or Paul
 Jordan TuttleMortgage and Equity Release AdviserCeMAP, Cert CII (MP & ER)
 Paul HaydonMortgage Adviser and DirectorCert CII (MP & ER)
The Mortgage Hive Ltd is authorised and regulated by the Financial Conduct Authority (FCA 844138).
Mortgage advice questions, answered
Do you charge a fee for mortgage advice?
No, we don’t charge an advice fee. Lender, valuation and legal costs may apply, and we explain them before you decide anything.
How are you paid?
We don’t charge a broker fee. We’re paid by the lender or provider. Lender, valuation and legal costs may apply.
Do you only help people in one area?
No. We give mortgage and protection advice to clients anywhere in England and Wales, by phone or video. Equity release advice is available in England only. Get in touch to arrange a time.
Can you help if I’m self-employed or have had credit problems?
Often, yes. Self-employment, a past missed payment, a CCJ or income from several sources can narrow the choice of lenders, but it doesn’t always rule you out. Tell us the details and we’ll explain where you stand.
Will an enquiry affect my credit score?
Sending us an enquiry won’t affect your credit score. A lender may run a credit search later in the process. We explain when that could happen, and whether it’s a soft or hard search, before anything is submitted.
What is a Decision in Principle?
It’s a lender’s early indication of how much it may be willing to lend, based on the details you give. It isn’t a mortgage offer, and the lender will still check your full application, documents, credit file and the property.
Do you arrange life insurance and income protection?
Yes. We advise on life insurance, critical illness cover and income protection, either alongside your mortgage or on its own.
Do you advise on equity release?
Yes, for homeowners aged 55 and over. We’re members of the Equity Release Council and we explain the risks and the alternatives first. Equity release includes lifetime mortgages and home reversion plans. To understand the features and risks, ask for a personalised illustration. Equity release will reduce the value of your estate and may affect your entitlement to means-tested benefits. Equity release advice is available in England only. Read about our equity release advice.
Start with a conversation
Tell us what you’re planning and we’ll explain your options, the costs and the next step. No pressure and no obligation.
- No advice fee
- 900+ clients
- ★ 5.0 from 59 Google reviews
- FCA 844138
Open Monday to Sunday, 9am to 9pm.
No advice fee. Lender, valuation and legal costs may apply. Looking for local advice? See our mortgage advice in Bournemouth.
