
Equity release costs and fees
How much does equity release cost?
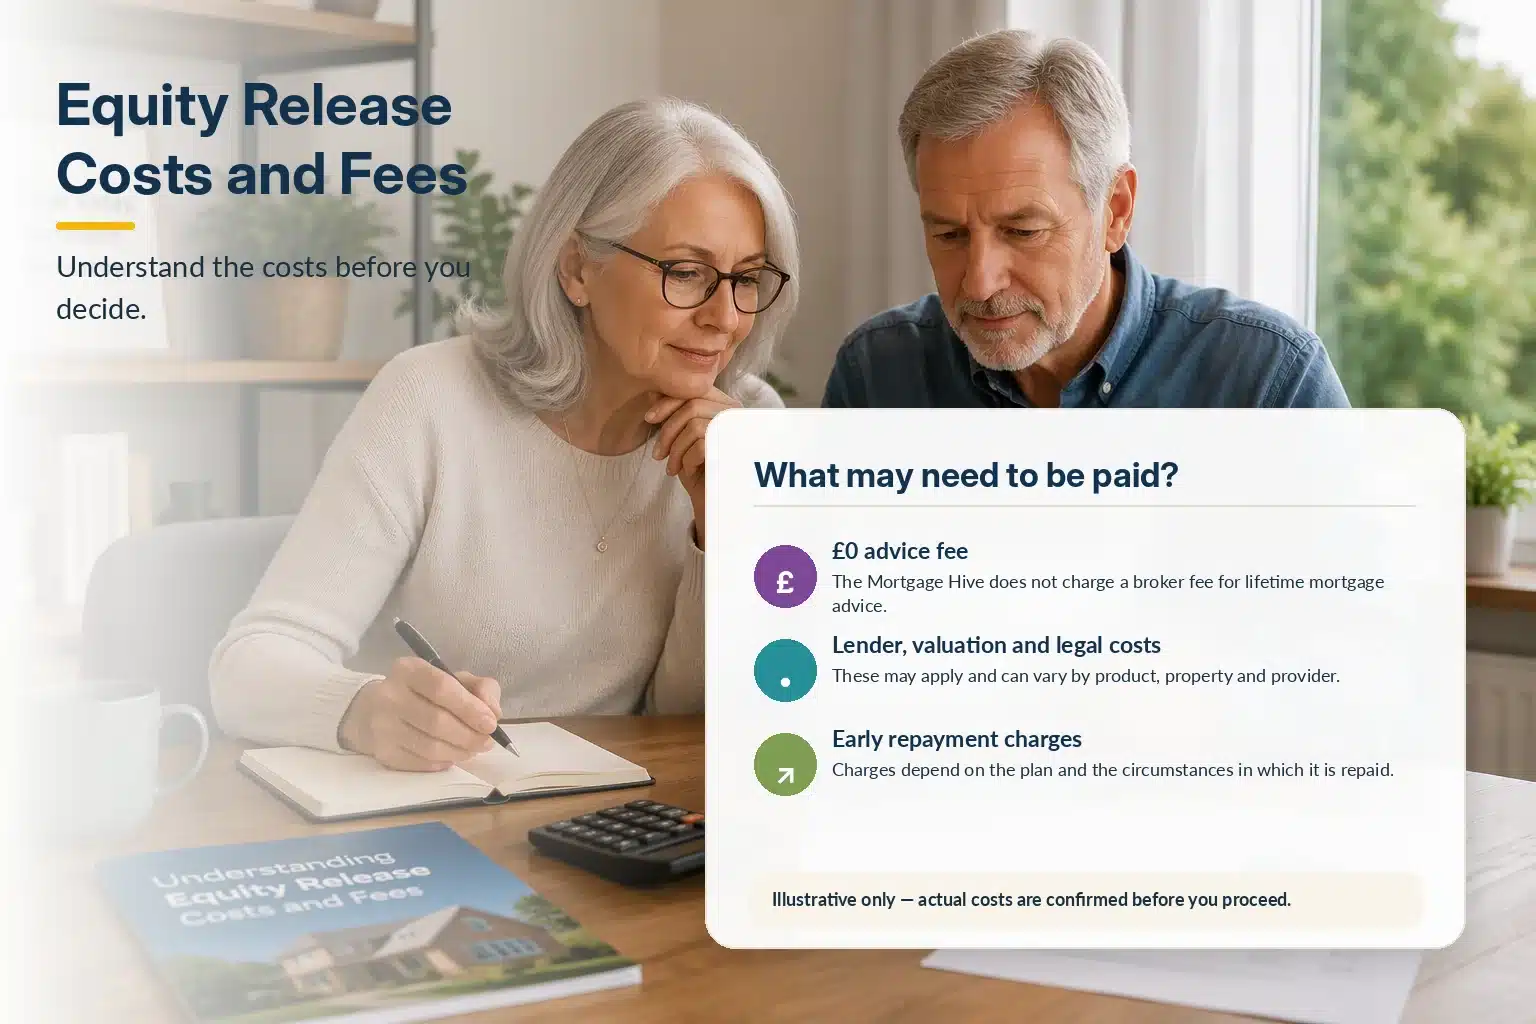
There is no single price. The cost of equity release is made up of set-up fees, which can include a lender fee, a valuation and a solicitor, and the interest charged over the life of the plan. For most people, interest is by far the biggest cost. The Mortgage Hive charges no advice fee.
The full picture
Every cost, in one place.
The costs below are the ones most people come across. Not every plan has every fee, and the amounts vary by lender, property and solicitor, so your own figures will be in your personalised illustration and quotations before you commit.
| Cost | What it is | When it’s paid | Can it be added to the loan? | Our note |
|---|---|---|---|---|
| Advice fee | Payment to the adviser for research and a recommendation | Usually on application or completion, where charged | Depends on the adviser | The Mortgage Hive charges £0 |
| Lender arrangement or product fee | The lender’s charge for setting up the plan | Usually on completion | Often, yes | Some plans have no arrangement fee, but may have a higher rate |
| Application or completion fee | A separate administration charge some lenders make | On application or completion | Sometimes | Ask whether it is refundable if the plan doesn’t go ahead |
| Valuation | The lender’s assessment of your home’s value | Usually before the offer | Rarely | Some lenders include a free standard valuation |
| Solicitor (legal fees) | Independent legal advice and the conveyancing work | On completion, plus some costs during the case | Sometimes | Required under Equity Release Council standards |
| Transfer and admin charges | Bank transfer, identity check and similar small charges | On completion | Sometimes | Usually small, but should be listed |
| Interest | The cost of borrowing over the years | Added to the loan each month or year, unless you choose to pay it | It rolls up onto the loan if unpaid | Usually the largest cost by far |
| Early repayment charges | A charge if you repay early or overpay beyond your allowance | Only if you repay early | No | Depends on the plan; some exemptions may apply |
On a phone, scroll the table sideways to see every column.
Clear advice, not pressure
Our advice fee: £0
The Mortgage Hive does not charge a broker or advice fee for equity release or later-life mortgage advice. If we recommend a lifetime mortgage and it completes, the lender may pay us commission. That doesn’t change what you pay the lender.
Lender, valuation and legal costs can still apply. We set them out before you decide anything, so you know what is payable upfront, what can be added to the loan and what you would pay if you chose not to go ahead.
The long-term cost
The biggest cost is usually the interest
Set-up fees are a one-off. Interest builds up for as long as the plan runs.
On a standard lifetime mortgage you don’t make monthly payments, so interest is added to the loan. Next time interest is calculated, it is charged on the original amount and on the interest already added. This is compound interest. It means the balance grows slowly at first and more quickly over time.
That’s why a plan with no arrangement fee isn’t automatically cheaper. A slightly higher rate on a plan you keep for many years can cost more than a one-off fee. It is also why adding fees to the loan matters: interest can then be charged on those fees for the life of the plan.
Ways to reduce the interest cost
- Borrow only what you need. A drawdown lifetime mortgage lets you take a smaller amount now and more later, so interest is only charged on money you’ve taken.
- Make voluntary repayments. Many plans let you repay part of the loan each year without a charge. See voluntary repayment lifetime mortgages.
- Pay the interest monthly. An interest-paying lifetime mortgage can stop the balance growing, if the payments are affordable.
For more on how rates are set and compared, read our guide to equity release interest rates.
If plans change
Early repayment charges
Lifetime mortgages are designed to last for the rest of your life, or until you move into long-term care. If you repay early, or pay more than your plan’s penalty-free allowance, an early repayment charge may apply.
Plans work this out in different ways. Some use a fixed percentage that reduces over a set number of years. Others use a variable calculation linked to movements in government bond (gilt) yields, so the charge could be higher or lower depending on market conditions at the time.
A charge may not apply in some situations. The most common are set out in the panel on this page.
These exemptions differ between lenders and come with conditions, such as time limits or a minimum period since the plan started. Your personalised illustration and mortgage offer set out the exact rules. If you already have a plan, see can I pay off my equity release early?
Before anything is paid
Fees you might pay if you don’t go ahead
Some costs are paid before the plan completes. If your application is declined, or you decide not to proceed, you may not get these back. This can include a valuation fee, a lender application fee and work your solicitor has already done.
Before anything is paid, ask the questions in the panel on this page. We’ll answer them for your case before you apply.
No guesswork
How to see the full cost before you commit
You won’t need to guess. Before you apply, you will receive a personalised illustration from the lender, setting out the rate, every fee, how the balance could grow and the early repayment terms.
Your solicitor will also give you a quote for the legal work. We go through all of this with you, and with family members if you’d like them there, so you can compare the full cost with the alternatives, such as downsizing or a retirement interest-only mortgage.
The balanced view
Things to weigh up.
Both sides of the cost should be clear before any application.
What can keep costs down
- Comparing the full cost, not just the headline rate.
- No advice fee from The Mortgage Hive.
- Some products include a free valuation or have no arrangement fee.
- Repayment features can reduce long-term interest.
- Personalised illustrations show projected balances before you commit.
What you must consider
- Adding fees to the loan means interest may build up on them.
- A small difference in the interest rate can make a large difference over many years.
- Early repayment charges can limit what you can do later.
- Legal and valuation costs are usually higher for complex properties, such as some leasehold flats or homes of non-standard construction.
- Borrowing more than you need increases the total cost.
- Equity release will reduce the value of your estate and may affect entitlement to means-tested benefits.
Consumer protection
Safeguards and responsibilities.
Council-standard lifetime mortgage protections apply subject to the plan terms and lender criteria. Other later-life products can have different protections.
Experience and accountability
Why choose The Mortgage Hive?
Later-life mortgages are long-term, regulated commitments. The quality of the advice matters because the lowest headline rate is not enough if the product lacks suitable flexibility, conflicts with future plans or overlooks a better alternative.
The Mortgage Hive provides fee-free mortgage and equity release advice across the UK and welcomes family members into the conversation where the homeowner wants them involved.
Last reviewed: October 2026. General information only; personal suitability depends on your individual circumstances.
Common questions
Equity release costs and fees FAQs.
These answers are general. A recommendation can only be made after your circumstances and alternatives have been assessed.
How much does equity release cost?
There’s no fixed figure. Set-up costs can include a lender fee, valuation and solicitor’s fees, and these vary by lender, property and law firm. The biggest cost is usually the interest added over the years. Your personalised illustration shows the full cost of a specific plan before you commit.
Does The Mortgage Hive charge an advice fee?
No. We charge £0 for equity release advice. If a lifetime mortgage we recommend completes, the lender may pay us commission. Lender, valuation and legal costs may still apply, and we explain each one before you decide.
Can the fees be added to the loan?
Some lender fees can be added to the mortgage or taken from the money released, so you don’t pay them upfront. The downside is that interest may then be charged on those fees for the life of the plan. Paying them from savings can reduce the long-term cost, if you can comfortably afford to.
Do I have to pay for a valuation?
It depends on the lender. Some include a free standard valuation; others charge a fee, often based on the property’s value. Unusual properties may need extra reports, which can add cost. We’ll tell you what applies before you apply.
Why do I need a solicitor, and who pays?
Independent legal advice is a requirement under Equity Release Council standards. Your solicitor explains the legal commitment and confirms you understand it and are acting freely. You normally pay the legal fees, although some lenders offer help towards them.
Will I pay anything if I decide not to go ahead?
You may. A valuation fee, lender application fee or legal work already done might not be refundable. Ask which fees are payable upfront and which are refundable before anything is paid.
Is the lowest rate always the best choice?
No. Product flexibility, future withdrawals, repayment options and charges can matter as much as the rate. A plan with a slightly higher rate but lower fees or better features may suit you better.
Get a clear answer
See the full cost before you decide.
We’ll show you every fee, how the balance could grow and how it compares with the alternatives. No advice fee and no obligation to go ahead.
Important information: Equity release includes lifetime mortgages and home reversion plans. To understand the features and risks, ask for a personalised illustration. A lifetime mortgage is secured against your home. Equity release will reduce the value of your estate and may affect entitlement to means-tested benefits. It may involve early repayment charges and can affect future financial flexibility. Retirement interest-only and other payment-based mortgages require payments to be maintained and your home may be repossessed if you do not keep up repayments. Home reversion plans involve selling part or all of your home. The Mortgage Hive does not charge an advice fee; lender, valuation and legal costs may still apply. This page provides general information and is not a personal recommendation, mortgage offer or legal, tax or benefits advice.