
Fixed, capped and compound interest explained
Equity release interest rates explained.
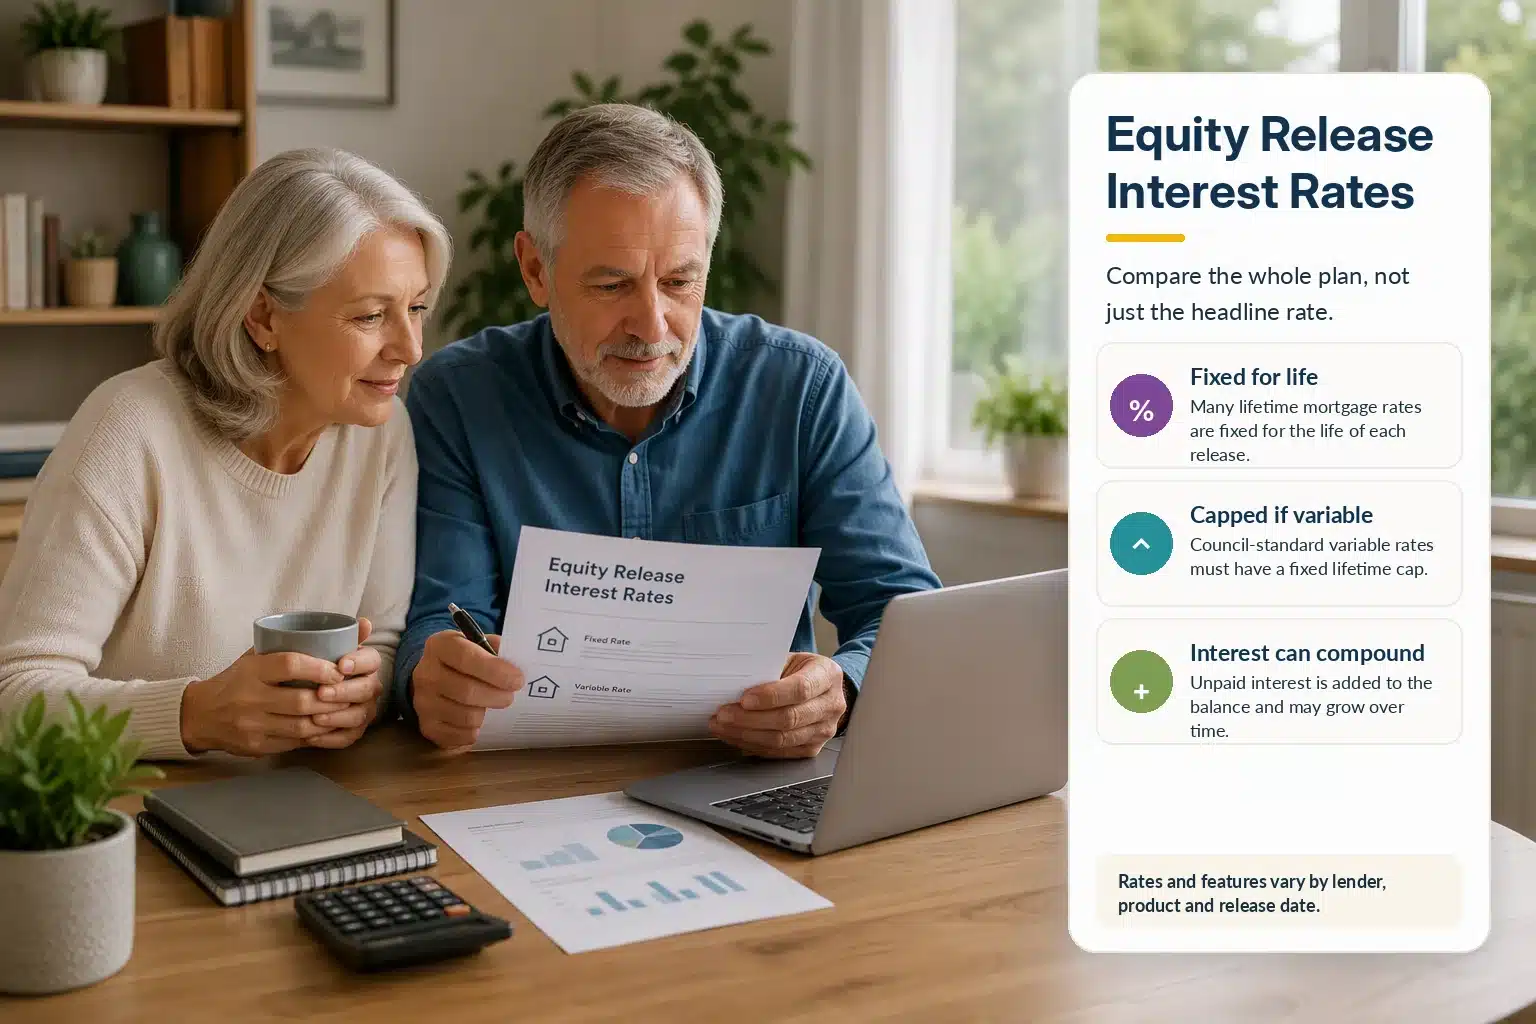
Equity release interest rates are normally fixed for life, so the rate on each amount you release does not change. Some plans use a variable rate instead, but under Equity Release Council standards it must have a lifetime cap. Unless you choose to make payments, the interest is added to the loan and compounds over time. We don’t publish rates on this page, because the only rate that matters is the one offered to you in a personalised illustration. This guide explains how rates work, what affects them and how to compare plans.
The clear answer
How lifetime mortgage interest rates work
Most lifetime mortgages charge a rate that is fixed when you take the money and stays the same for the life of the plan. That gives you certainty: the rate on that release will not rise if interest rates in the wider market go up.
Some plans offer a variable rate instead. For plans that meet Equity Release Council product standards, a variable rate must have a fixed upper limit (a cap) that applies for the life of the mortgage.
On a standard roll-up plan you make no monthly payments. Each year’s interest is added to the loan, and the next year interest is charged on the larger balance. That is compound interest. See how compound interest works on equity release for a step-by-step explanation.
If you have a drawdown plan, each later withdrawal from your reserve normally takes the rate available on the day you draw it. That rate may be higher or lower than your original rate. The reserve itself is not guaranteed, so lenders can change or withdraw it.
Plans that meet Equity Release Council standards also include the no negative equity guarantee. As long as the plan’s conditions are met, you or your estate will not owe more than the home is worth when it is sold, however much interest has built up.
How lenders price a plan
What affects the rate you’re offered
Lenders price each plan individually. We don’t publish a single “typical” rate, because the rate that matters is the one offered on your circumstances. Your personalised illustration will show it.
The amount you borrow
How much you borrow compared with your home’s value. Borrowing a smaller share of the value can open up a wider choice of plans.
Your age
Age mainly affects how much you can borrow, which in turn affects the products available to you. With joint applicants, the youngest person’s age is used.
Your property
Its value, type, construction and location affect which lenders will consider it. The lender’s own valuation is what counts.
Plan type and features
A lump sum, a drawdown plan, an interest-paying plan, inheritance protection and payment options can all affect pricing.
Health and lifestyle
Enhanced plans may offer different terms where certain health or lifestyle factors apply.
Market conditions
Lender pricing changes over time, so a rate available today may not be available next month.
Why the balance grows
How compound interest changes the balance
On a standard roll-up lifetime mortgage you make no monthly payments. Interest is added to the loan, and the following year interest is charged on the larger balance, including the interest already added. It means the balance grows slowly at first and faster as the years go on.
Year 1
Interest is charged on the amount you released.
Year 2
Interest is charged on the amount released plus year 1’s interest.
Year 3
Interest is charged on the loan plus the interest added in years 1 and 2.
Every year after
Each year’s interest is bigger than the one before, unless you make payments.
The effect depends on the rate, the amount, any fees added to the loan, any payments you make and how long the plan runs. To see how it could look, try the lifetime mortgage calculator and the voluntary repayment calculator. A personalised illustration shows projections based on your actual plan.
Keeping interest under control
Ways to limit the cost
The rate is fixed, but how much interest builds up is partly in your hands.
Borrow only what you need
Interest is charged on every pound released, so a smaller release means less interest builds up.
Use drawdown for future needs
With a drawdown plan you take an initial amount and keep a reserve. Interest is normally charged only on money you actually withdraw. Not sure which suits you? Compare lump sum or drawdown.
Make voluntary payments
Many plans let you repay part of the loan or the interest without a charge, up to a limit set by the lender. Paying above that limit can trigger early repayment charges: see what early repayment charges apply to equity release.
Consider an interest-paying plan
Some lifetime mortgages let you, or require you to, pay some or all of the interest each month. That can stop the balance growing, but the payments must be affordable.
Avoid adding fees to the loan where practical
Fees added to the loan attract interest over the life of the plan.
Look beyond the headline rate
How to compare rates properly
The headline rate is only part of the picture. A plan with a slightly higher rate but more flexibility may suit you better than one that only looks attractive on rate. When comparing plans, look at:
The APRC
The annual percentage rate of charge combines the interest rate with certain fees, based on stated assumptions, so it allows fairer comparison.
Fees
Arrangement, valuation and legal costs, and whether each is paid upfront or added to the loan. See equity release costs and fees.
Early repayment charges
How they are calculated, how long they last and when they don’t apply. See what early repayment charges apply to equity release.
Payment flexibility
How much you can repay each year without a charge.
Drawdown terms
How the reserve works and how later withdrawals are priced.
Features you may need
Inheritance protection, downsizing protection and the right to move the plan to a new home (subject to lender criteria).
We compare these alongside the rate, and explain the trade-offs in plain English before any recommendation.
The balanced view
Risks to understand
- Lifetime mortgage rates are often higher than standard residential mortgage rates. If you can afford monthly payments, a retirement interest-only mortgage may be worth comparing.
- Compound interest can make the balance grow significantly over a long period.
- Rates on later drawdowns may be higher than your original rate.
- Switching to a different plan later may involve early repayment charges and new fees.
- Equity release will reduce the value of your estate and may affect your entitlement to means-tested benefits.
Consumer protection
Safeguards and responsibilities.
Council-standard lifetime mortgage protections apply subject to the plan terms and lender criteria. Other later-life products can have different protections.
The Mortgage Hive approach
Clear advice, not pressure.
We start with the outcome you want, assess the wider picture and compare suitable later-life lending routes only after realistic alternatives have been considered.
Experience and accountability
Why choose The Mortgage Hive?
Later-life mortgages are long-term, regulated commitments. The quality of the advice matters because a rate that looks attractive is not enough if the plan lacks suitable flexibility, conflicts with your future plans or overlooks a better alternative.
Our equity release advisers, Jordan, Paul and Perera, are all equity release qualified. We give advice across England by phone or video, with home visits by arrangement anywhere in England, and welcome family members into the conversation where you want them involved. Our office is in Winton, Bournemouth, and we have helped over 900 clients.
Some of the lenders we can arrange equity release with: Aviva, Canada Life, Just, Legal & General, LV=, more2life, OneFamily and Pure Retirement.
Last updated: October 2026. General information only; personal suitability depends on your individual circumstances.
Real figures
Why a personalised illustration is the only way to see real figures
A guide like this can explain how rates work, but it can’t tell you what you would pay. A personalised illustration is the formal document a lender provides, based on your age, your home, the amount you want and the plan you choose. It shows the rate for that plan, the fees, the early repayment charges and how the balance could grow over time, including the effect of any voluntary repayments.
To get an idea of the amount first, try the equity release calculator. To see how interest could build up, use the lifetime mortgage calculator, then talk to an adviser about your own figures.
Common questions
Equity release interest rate FAQs
These answers are general. A recommendation can only be made after your circumstances and alternatives have been assessed.
Are equity release interest rates fixed?
Most lifetime mortgage rates are fixed for life on each amount you release. Some plans use a variable rate. Under Equity Release Council standards, any variable rate must have a cap that applies for the life of the plan, so it cannot rise above that limit. If you take money in stages with a drawdown plan, each later withdrawal normally takes the rate available on the day you draw it.
What are typical, average or current equity release interest rates?
There is no single typical or average rate that applies to everyone, and we don’t quote rates on this page. Rates change with the market and depend on your age, how much you borrow compared with your home’s value, your property and the plan features you choose. Your personalised illustration shows the rate available to you and the projected balance over time.
How can I compare equity release interest rates?
Compare plans like for like, using personalised illustrations, and look beyond the rate. Check the APRC, which combines the interest rate with certain fees based on stated assumptions. Then look at fees, early repayment charges, how much you can repay each year without a charge, how drawdown works and the features you may need. Switching later means repaying the current plan, which may involve early repayment charges and new fees. Our guide to equity release costs and fees covers the costs.
Why are equity release interest rates higher than normal mortgage rates?
Lifetime mortgages normally run until the last borrower dies or moves into long-term care, often with no monthly payments. The lender doesn’t know when it will be repaid, and plans that meet Council standards include a no negative equity guarantee. These factors are reflected in pricing. If you can afford monthly payments, a retirement interest-only mortgage may be worth comparing.
How does compound interest work on equity release?
On a standard roll-up plan, interest is added to the loan each year and then charged on the larger balance, so the amount owed grows faster the longer the plan runs. Our answer on how compound interest works on equity release explains it step by step. The no negative equity guarantee on Council-standard plans means you or your estate will not owe more than the home is worth when it is sold, as long as the plan’s conditions are met.
Can I pay the interest to stop the balance growing?
Often, yes. Many plans allow voluntary payments up to a set limit each year without a charge, and some interest-paying plans let you pay all the monthly interest. Paying above the allowed limit may trigger early repayment charges: see what early repayment charges apply to equity release. The voluntary repayment calculator shows how optional payments could change the balance.
Get a clearer answer
See the rate available to you
We’ll look at plans on rate, fees and flexibility, and show how the balance could grow before you decide. No adviser fee. Lender, valuation and legal costs may apply.
Important information: Equity release includes lifetime mortgages and home reversion plans. To understand the features and risks, ask for a personalised illustration. Equity release will reduce the value of your estate and may affect your entitlement to means-tested benefits. A lifetime mortgage is secured against your home. It may involve early repayment charges and can affect future financial flexibility. Retirement interest-only and other payment-based mortgages require payments to be maintained and your home may be repossessed if you do not keep up repayments. Home reversion plans involve selling part or all of your home. No adviser fee. Lender, valuation and legal costs may apply. This page provides general information and is not a personal recommendation, mortgage offer or legal, tax or benefits advice.