
Does Spray Foam Insulation Stop You Getting Equity Release?
It can make equity release more difficult, but it is not an automatic universal ban. The outcome depends on the foam type, installation quality, roof condition, paperwork, ventilation and the lender's valuation policy.
However, the presence of foam does not always mean the property is unmortgageable. The lender will consider the type of foam, where and how it was installed, supporting paperwork, the condition of the roof and any specialist report. Some cases may proceed with satisfactory evidence; others may require partial or complete removal and repairs before a lender will accept the property.
Why does spray foam cause lender concerns?
Spray polyurethane foam is applied to the underside of a roof or other surfaces to improve insulation. The difficulty for a valuer is that the foam can obscure timbers and make it harder to see moisture, decay or defects. Poorly designed installations may also alter ventilation and moisture movement.
RICS guidance stresses that spray foam should be treated as a serious property modification and assessed on its facts. The practical issue is not simply that foam exists, but whether the roof remains sound, inspectable and saleable.
Important: Be cautious about firms that say every installation must be removed immediately or guarantee that removal will make the property mortgageable. Obtain independent professional advice before committing to expensive work.
Does the type of foam matter?
Yes. Open-cell and closed-cell products behave differently, and the location and method of installation matter. A valuer may want to know the product used, the installer, the date, any warranty and whether a proper survey preceded installation.
What paperwork could help?
Useful evidence may include the installation contract, product specification, warranty, roof survey, moisture assessment, ventilation design and photographs taken before and during the work. Missing paperwork does not prove the roof is defective, but it can make the lender's decision harder.
Will a specialist report solve the problem?
A report from an appropriately qualified and independent surveyor or building professional may help explain the roof condition and risks. It does not compel a lender to accept the property, because each lender still applies its own policy.
Should the foam be removed?
Removal may be necessary where the installation is defective, the roof cannot be inspected or no lender will accept it. Removal can also damage roof coverings or timbers if done badly, so it should be planned with independent advice rather than treated as a simple cosmetic job.
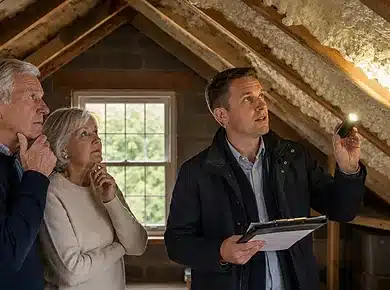
Three spray-foam outcomes that may differ
The evidence and roof condition can matter more than the label alone.
Full paperwork and a sound roof
A lender may still consider the property where the installation is documented and an inspection supports the roof's condition.
Foam conceals the entire roof structure
Where timbers cannot be inspected, the valuer may be unable to provide acceptable security advice without further investigation or removal.
Removal has already taken place
The lender may still require evidence that the foam was removed correctly and that the roof is dry, ventilated and structurally sound.
What should you do before making an application?
The aim is to establish the property facts before paying avoidable valuation, legal or removal costs.
Evidence to gather
- Installer and product details
- Any warranty or certification
- Pre-installation roof survey
- Ventilation and moisture information
- Independent roof-condition report
What this means in practice
- Some lenders may decline immediately
- Others may consider strong supporting evidence
- Removal is not always the first or only step
- A report cannot guarantee lender acceptance
- Early screening can save time and money
Your questions answered
Is all spray foam insulation unacceptable?
No. There is no single market-wide answer, but many lenders are cautious and some will not accept it.
Can I remove spray foam myself?
That is generally unwise. Poor removal can damage the roof and may not provide the evidence a lender needs.
Will a warranty make the property acceptable?
A warranty may help, but it does not replace a valuation or guarantee acceptance.
Can equity release funds be used to remove the foam?
Usually the property must be acceptable security before completion, so removal or remedial work may need funding in advance.
Understand the roof condition before choosing the next step.
This page provides general information, not personal advice. The Mortgage Hive can help you identify likely lender concerns and the evidence to obtain before applying.
Request a call back
Leave your details and an adviser will call you at a time that suits. There is no obligation to go ahead.
This page is general information, not personal advice. Equity release includes lifetime mortgages and home reversion plans. To understand the features and risks, ask for a personalised illustration. Equity release will reduce the value of your estate and may affect your entitlement to means-tested benefits.