
Can I Use Equity Release to Fund Home Care or Adapt My Property?
Yes. Lifetime mortgage funds can be used for paid care at home, accessibility work, mobility equipment and property adaptations. Before borrowing, check benefits, local authority support, grants and how long ongoing care costs may continue.
Before borrowing, the homeowner should check eligibility for Disabled Facilities Grants, local authority support, NHS-funded services, attendance-related benefits and other assistance. Ongoing care is particularly difficult to fund because the total duration and future cost are uncertain. A drawdown reserve may match staged expenditure better than a large lump sum, but releasing capital can affect means-tested support and leave less equity available if residential care is later required.
Using housing wealth to remain independent at home
Many homeowners would prefer to stay in familiar surroundings rather than move. Adaptations and paid support can make that possible for longer.
One-off building work is easier to budget than open-ended care. A bathroom conversion has a defined quotation, whereas daily care costs may continue and increase for years.
The adviser should therefore distinguish between funding a project and creating a sustainable care budget. Public support, benefits and specialist care advice should be considered before property wealth is used.
Important: Releasing money before checking grants or local authority support could reduce entitlement or cause the homeowner to pay privately for costs that might otherwise have been assisted.
What adaptations can be funded?
Possible uses include ramps, door widening, lifts, accessible bathrooms, downstairs bedrooms, heating improvements, security systems and mobility equipment.
Major structural work should be properly specified, costed and checked against lender consent requirements where applicable.
Can it pay for carers at home?
Yes. Funds may be used for agency care, personal assistants, respite or domestic support.
Because the cost is ongoing, the plan should estimate different care durations and inflation rather than focusing only on the first year.
What public support should be checked?
Depending on circumstances, support may include a local authority care assessment, Disabled Facilities Grant, Attendance Allowance, Personal Independence Payment, NHS Continuing Healthcare or other local schemes.
Entitlement rules are complex and may require independent specialist assessment.
What happens if residential care is needed later?
If the last borrower permanently leaves the property for long-term care, the lifetime mortgage normally becomes repayable under its terms.
Using a large share of the property equity for home care may reduce the resources available for a later move or care contribution.
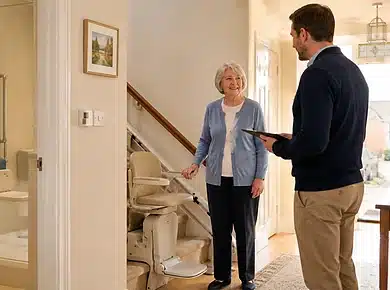
Three independence-at-home uses
The suitable funding structure depends on whether the cost is fixed, staged or ongoing.
A defined bathroom adaptation
The homeowner obtains quotations and releases only the required amount after checking grant eligibility.
Weekly care visits
A drawdown reserve is considered to fund care in stages, with scenarios showing how quickly it could be used.
The property may soon be unsuitable
Before major borrowing or building work, the homeowner compares adapting the home with moving to more suitable accommodation.
Adapt the home, pay for care or move?
Remaining at home may be the preferred outcome, but the property and care arrangement must remain practical and financially sustainable.
Questions worth considering
- What support is available without borrowing?
- Is the cost one-off or ongoing?
- How long could care be required?
- Will the property remain suitable after adaptation?
- What equity should remain for future care or moving?
What this means in practice
- Adaptations and home care are usually permitted uses.
- Grants and benefits should be checked first.
- Drawdown may suit staged costs.
- Ongoing care is difficult to predict.
- Permanent care can trigger repayment of the plan.
Your questions answered
Can equity release pay for a live-in carer?
Potentially, yes, but the long-term affordability and sustainability of the care arrangement must be assessed.
Will adaptations increase the property value?
Some may, while highly personalised work can have limited or mixed resale value. The primary purpose should be suitability and safety rather than assumed profit.
Do I need lender permission for building work?
Routine improvements may not require it, but structural alterations or major changes can. Check the mortgage conditions before work begins.
Can I use equity release if I already receive care benefits?
Potentially, but the released capital and spending pattern may affect means-tested support. A benefits review is important.
Check support and future care needs before using the home.
This page provides general information, not care or benefits advice. The Mortgage Hive can assess the mortgage options and coordinate with appropriate care, benefits and legal specialists.
Request a call back
Leave your details and an adviser will call you at a time that suits. There is no obligation to go ahead.
This page is general information, not personal advice. Equity release includes lifetime mortgages and home reversion plans. To understand the features and risks, ask for a personalised illustration. Equity release will reduce the value of your estate and may affect your entitlement to means-tested benefits.