
Can My Family Attend My Equity Release Advice Meeting?
Yes. You can normally invite adult children or another trusted person to an equity release advice meeting. Their involvement can improve understanding, but the adviser must establish that the decision is yours and may need to speak with you privately.
Family members can help remember information, ask questions and understand the effect on inheritance. However, the adviser’s duty is to the homeowner or borrowers. They must be satisfied that the client understands the recommendation, has capacity and is acting freely. The adviser may therefore ask to speak with the homeowner alone. The independent solicitor will also need to verify understanding and freedom from pressure and may conduct part of the legal meeting privately.
How family can be involved without taking over the decision
Equity release often affects the whole family because it can reduce inheritance and influence future housing or care choices. Open discussion can prevent surprises and help beneficiaries understand why the plan was chosen.
Family involvement is encouraged where the homeowner wants it, but it is not the same as family approval. The homeowner remains the client and controls what financial information can be shared.
Advisers and solicitors also need to remain alert to coercion, financial abuse and conflicts of interest, especially where a family member will receive some of the money.
Important: A family member attending the meeting does not become the client, gain authority over the application or receive a right to confidential information without the homeowner’s permission.
What can a family member contribute?
They can help explain family circumstances, ask about inheritance, care, moving home and repayment options, and support the homeowner in remembering complex information.
They should not answer every question on the homeowner’s behalf or pressure them towards a particular outcome.
Why might the adviser ask to speak to me alone?
A private conversation helps the adviser confirm that the homeowner understands the plan and is making the decision voluntarily.
It also gives the homeowner a safe opportunity to disclose concerns, family pressure or information they do not want shared.
Can family see the recommendation and illustrations?
Only with the client’s consent and subject to data-protection and confidentiality requirements.
The homeowner can agree that specified family members receive documents or join discussions, but can also withdraw that permission.
What if a child is receiving the released money?
The adviser should explore the homeowner’s own needs, the reason for the gift and whether any pressure exists.
The child’s benefit from the transaction creates a potential conflict, making independent client confirmation and careful documentation particularly important.
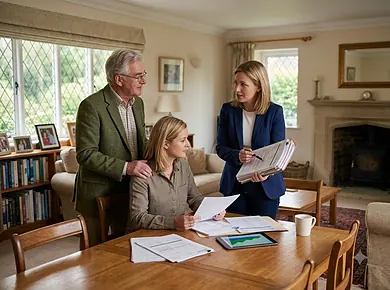
Three ways family may be involved
The level of involvement can be tailored to the homeowner’s preferences and circumstances.
A child attends the whole meeting
The homeowner gives permission, and the child listens and asks questions. The adviser still directs key questions to the homeowner.
The homeowner wants privacy
The advice takes place confidentially. The homeowner may choose to tell family later or not at all.
A family member will receive a gift
The adviser spends time alone with the homeowner to confirm the purpose, understanding and absence of pressure.
How much family involvement feels helpful?
Openness can build trust, but the homeowner should retain control over the meeting and personal information.
Questions worth considering
- Who do you trust to support the discussion?
- What information are you comfortable sharing?
- Will anyone receive some of the released money?
- Would a private conversation make you more comfortable?
- Should family receive copies of documents?
What this means in practice
- Family attendance is normally optional.
- The homeowner remains the client.
- Confidentiality requires the client’s consent.
- Private adviser and solicitor conversations may be needed.
- Pressure or conflict must be identified and managed.
Your questions answered
Can my child speak to the adviser without me?
Only within the authority and consent you provide. The adviser cannot disclose confidential client information freely to relatives.
Do all my children need to be invited?
No. You decide whom to involve. The adviser may discuss possible family tension but cannot require equal attendance by all beneficiaries.
Can a family member interpret for me?
An independent professional interpreter may be preferable where important regulated and legal information is involved, particularly if the relative could benefit from the transaction.
Can my family veto the recommendation?
No, not merely because they disagree. Ownership, capacity, legal authority and the homeowner’s informed wishes determine who can make the decision.
Make family involvement supportive, not controlling.
This page provides general information, not personal advice. The Mortgage Hive can include trusted family members while preserving confidentiality and independent decision-making.
Request a call back
Leave your details and an adviser will call you at a time that suits. There is no obligation to go ahead.
This page is general information, not personal advice. Equity release includes lifetime mortgages and home reversion plans. To understand the features and risks, ask for a personalised illustration. Equity release will reduce the value of your estate and may affect your entitlement to means-tested benefits.